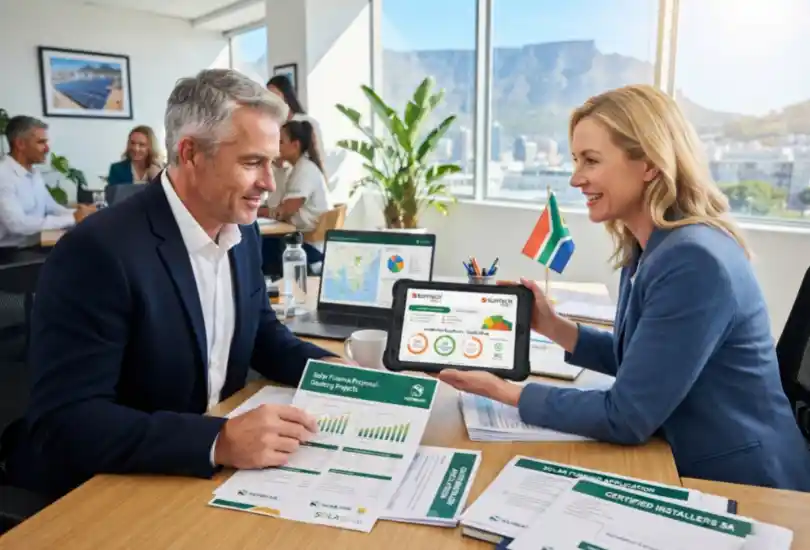
The financing decision behind commercial solar often matters as much as the system design itself — the same system can look like a great investment or a poor one purely depending on how it's paid for. South African businesses generally choose between three structures: a cash purchase, an asset or business loan, and a power purchase agreement (PPA). Each shifts risk and cost differently.
Cash Purchase
Paying upfront in cash delivers the best total long-term return of the three, since there's no financing cost layered on top and the business owns the asset outright from day one, including any tax depreciation benefits. The obvious trade-off is capital outlay — a meaningful sum tied up in one asset, which some businesses would rather deploy elsewhere (stock, staff, expansion) even if solar's own return looks attractive in isolation.
Cash purchase suits businesses with strong reserves and a long planning horizon for the property, where the multi-year total-cost advantage outweighs the opportunity cost of the capital.
Asset or Business Loan
Financing the purchase through a loan spreads the capital cost over time while still delivering ownership at the end (or immediately, depending on the loan structure) — a middle path between cash purchase and a PPA. The business pays interest on top of the system cost, reducing total return compared to cash, but preserves capital for other uses in the meantime.
This route makes sense when a business has creditworthiness for reasonable financing terms and wants ownership benefits without a large single cash outlay — the monthly loan repayment simply needs to compare favourably against the monthly electricity savings for the numbers to work.
Power Purchase Agreement (PPA)
Under a PPA, a third party owns and maintains the system, and the business simply buys the electricity it generates at an agreed rate — usually below the equivalent grid tariff — for a fixed contract term. No capital outlay, no maintenance responsibility, but also no ownership, and the electricity rate is locked into a contract rather than fully controlled by the business.
PPAs suit businesses that want solar-discounted electricity without touching capital budgets at all, or that don't want the maintenance and equipment risk that comes with ownership. The trade-off is a lower total long-term return than ownership, and less flexibility if the business wants to exit or renegotiate before the contract term ends.
Comparing Them on the Same Basis
The fair comparison isn't "which is cheapest" in isolation — it's total cost of electricity over the system's realistic lifespan, under each structure, weighed against how much the business values keeping capital free versus owning the asset outright. A PPA that looks more expensive over 15 years than a cash purchase may still be the right call for a business that genuinely can't or won't tie up that capital elsewhere.
Questions Worth Asking Before Choosing
- What's the total cost over the full term, under each option, not just the monthly number?
- For a PPA, what happens at contract end — transfer, renewal, or removal of equipment?
- For a loan, does the monthly repayment comfortably clear the monthly savings, with margin?
- Does the business's tax position make ownership depreciation benefits meaningful, or is that a lesser consideration?
Get a Baseline Before Comparing Financing Options
Our solar calculator gives a starting estimate of system size and cost, useful as the baseline figure to run through each financing structure's own math. When you're ready to get formal proposals — including from providers who structure PPAs — compare options on ADEO.
Frequently Asked Questions
Is a PPA rate guaranteed to be cheaper than grid electricity for the whole contract term? Typically it's set below the current grid tariff at signing, but confirm whether the PPA rate escalates over time and how that compares to expected grid tariff increases over the same period.
Can a business switch from a PPA to ownership later? Some PPA providers offer a buyout option at or before contract end — this varies by provider and should be confirmed in the contract terms upfront, not assumed.
Does financing through a loan affect eligibility for any tax incentives? Financing structure can affect how tax benefits are claimed and by whom — this is worth confirming with your accountant given your specific loan and business structure, rather than assuming it works the same as a cash purchase.
Writes about solar and renewable energy for South African homes and businesses at SolarTally, and cross-checks every guide against current tariffs and installer standards.


Popular on SolarTally